
A consequential decision. Especially since, for most people, pension fund assets account for the largest asset there is and need to last around 20 to 30 years. What’s more, the decision is final. Once you’ve made it, you can’t go back and fix it. Today, many people consciously choose a combination of pension and lump sum. The portion drawn as a pension makes it possible to plan while the lump sum portion creates flexibility for fulfilling dreams, for investments or for inheritance.
I’ll make a quick decision on how to use my pension assets just before retirement.
MISCONCEPTION
There’s no rule of thumb for getting the ratio right; life situations, goals and risk profiles are too individual. That’s exactly why personal advice makes all the difference. This involves maintaining an overview of the many influencing factors and combining them into a strategy that suits your life.
Report lump-sum withdrawals from your pension fund in good time
The lump-sum option must be reported to the pension fund at least one year before withdrawal; some regulations even require a notice period of three years in advance. If you’re making the decision at the last minute, you’ve already lost the battle.
Lump sum and/or pension decision-making aid
- Inflation: How can your income retain its purchasing power over a period of 20 to 30 years?
- Family insurance: What will remain for your partner or heirs in the event of your death?
- Investment options: How will the withdrawn capital be invested and managed?
- Life expectancy: How does this influence the weighting of pension and lump sum?
- Personal goals: How much predictability do you need; how much flexibility would you like?
- Tax: What are the tax effects of pensions and lump sums and can the withdrawal be staggered?
Pension planning – options for staggered lump sum withdrawal
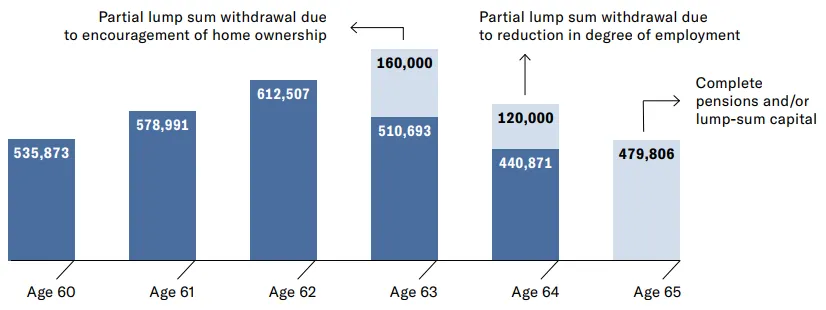
If you withdraw your pension fund capital all at once, you’ll pay tax on the full amount and progression will take full effect. If you stagger the withdrawal over several years, you’ll break this progression and save significantly on
the bottom line. The graph shows an example of how a withdrawal via partial lump-sum withdrawals for home ownership can be staggered with a reduction in the degree of employment and a pension or lump-sum withdrawal on retirement. The decisive factor is early planning, since the withdrawal window cannot be opened up retroactively.
Working beyond 65 – keeping an eye on the possibilities of the three pillars
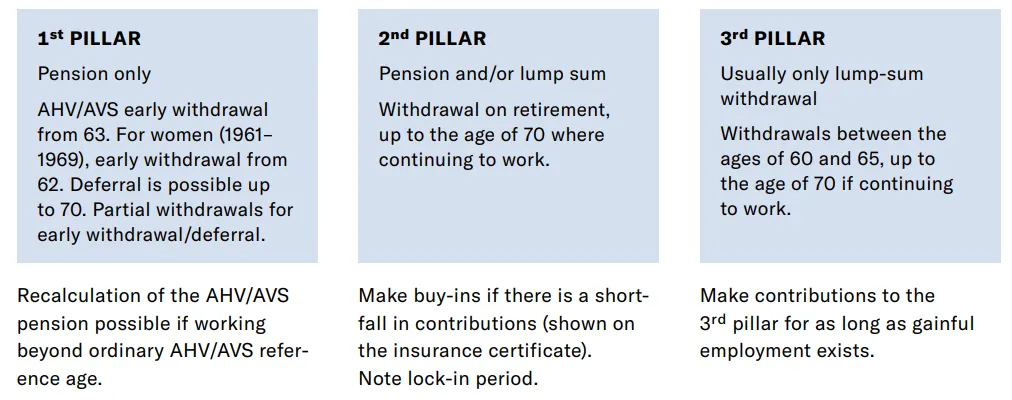
If you continue to work after the age of 65, each of the three pillars offers varying degrees of flexibility which do not automatically complement one another. AHV/AVS, can be withdrawn early or deferred. The pension fund allows for a pension, a lump sum or a combination, depending on the regulations, and the 3rd pillar a remains open in the event of continued gainful employment. The graph shows an overview of these options. Being familiar with these and coordinating these with one another can help you make a conscious transition into retirement rather than blindly accepting the standard path.
Suitable solutions

The individual pension solution 1e for employees with an annual income of CHF 136'080.– or above (2026 figures).

Our pension solution with a standardised strategy for employees with an annual salary of CHF 90'720.– (as at 2026) or more.

The customised vested benefits institution for your retirement lump-sum capital.
The independent vested benefits institution with an additional pension option.