
The underestimated compound interest effect
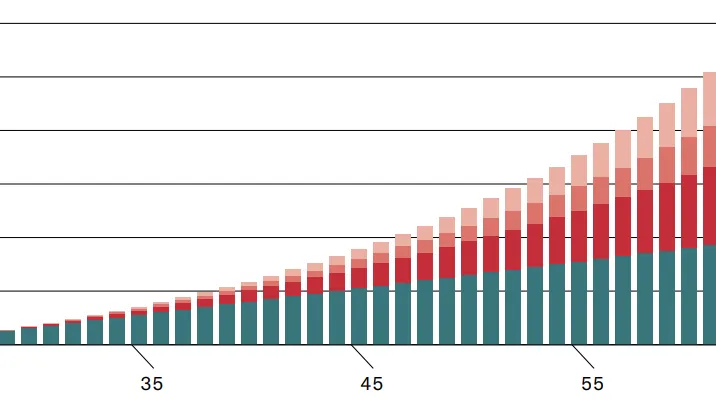
It is not uncommon for a 35-year-old to already have 100,000 Swiss francs or more saved in their pension fund. Even at an interest rate of 3 percent per annum, the compound interest effect will see the amount increase to around 243,000 Swiss francs by retirement. A lump-sum withdrawal to buy a home would eliminate this effect and also block voluntary purchases until the withdrawal is repaid in full.
We receive a lot of enquiries from young couples who want to draw pension assets to purchase their own home. We advise them to exercise caution here.
Juan M. Puente, Client manager
Pledge, don’t withdraw
One alternative is pledging, which offers more benefits than a lump-sum withdrawal. The bank deposits the 2nd pillar as collateral in the mortgage agreement. The retirement account remains in the pension fund and will continue to accrue interest. If a withdrawal is still necessary, it is better to use your pillar 3a retirement assets for this purpose.
I finance my apartment with pension fund assets, too.
MISCONCEPTION
Pension assets for home buying: the most important questions
- How much capital do I really need, and how much of it from my pension savings?
- What shortfall will a lump-sum withdrawal entail and how do I offset it?
- Would pledging be a better solution than a withdrawal?
- Can the required capital be drawn primarily from pillar 3a?