
A plan that fits every stage of life
More than an obligation
The law requires that employers insure their employees in a pension fund, but it only stipulates a minimum. For a business owner like Mauro Santin, his company’s pension fund solution is more than an obligation. It is an expression of his philosophy of life and a decisive factor in attracting and retaining good skilled workers.
In Stefano Minuscoli I have a partner who takes a human and forward-looking approach to my employees’ pension planning. This gives me time for what I love to do most: being there for my customers.
Mauro Santin, Owner and Managing Director TopPharm Neuenhofer Pharmacy
Elective plans appropriate to life stage
What employees receive in retirement, in the event of disability or in the event of death depends heavily on the solution chosen. In a mixed-age team, the needs are different. A 25-year-old employee has different life and pension goals than a colleague who is about to retire. Elective plans make it possible for each and everyone to choose the savings strategy that suits their own stage of life. This builds trust in the employer, in the company and in their future.
Pension solutions that pay off
Mauro Santin’s success relies on people who enjoy working for him because they feel supported and valued. A good pension fund solution contributes to this significantly.
Not all pension funds are the same
There are a number of questions that can determine whether or not a pension fund fits in with your company philosophy:
- Is it offering elective plans with real customisation options?
- Are the risks of death and disability adequately covered?
- How transparent is the solution for those counting on it?
- Is the interest rate of the pension fund competitive?
Elective plans – an interesting option
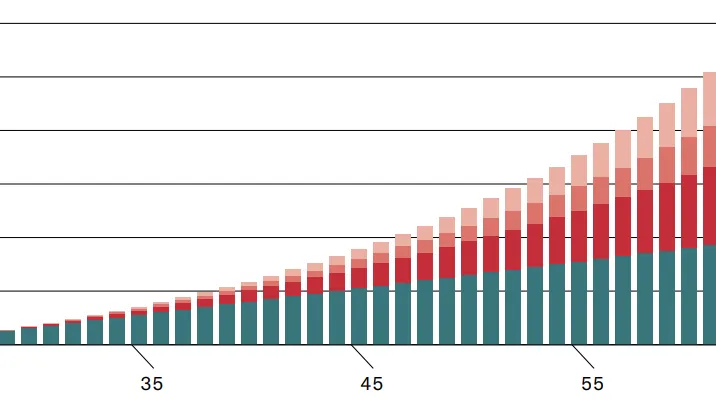
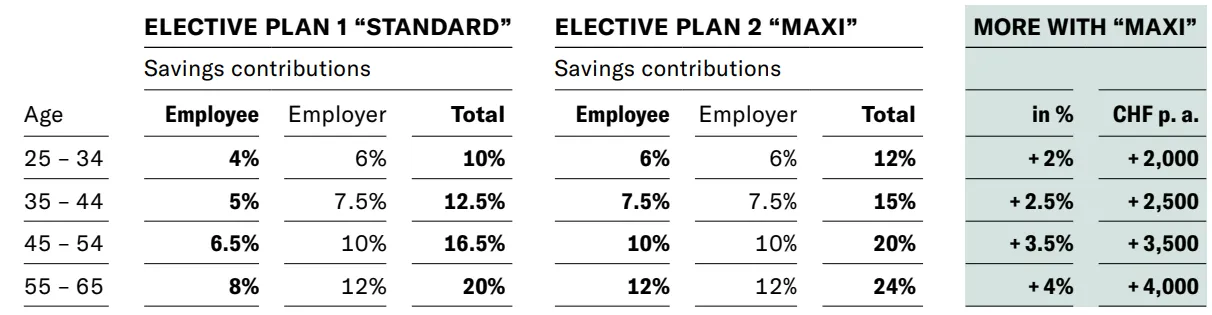
In the example above, the decision in favour of elective plans is cost-neutral for the employer. They make the same contribution in each elective plan, while employees are free to choose their savings option. With an insured salary of 100,000 Swiss francs, a 45 to 54-year-old employee can save 16,500 Swiss francs per year for retirement in the “Standard” elective plan, and 20,000 Swiss francs in the “Maxi” elective plan, i.e. 3,500 Swiss francs more, year after year.