When saving for retirement really starts

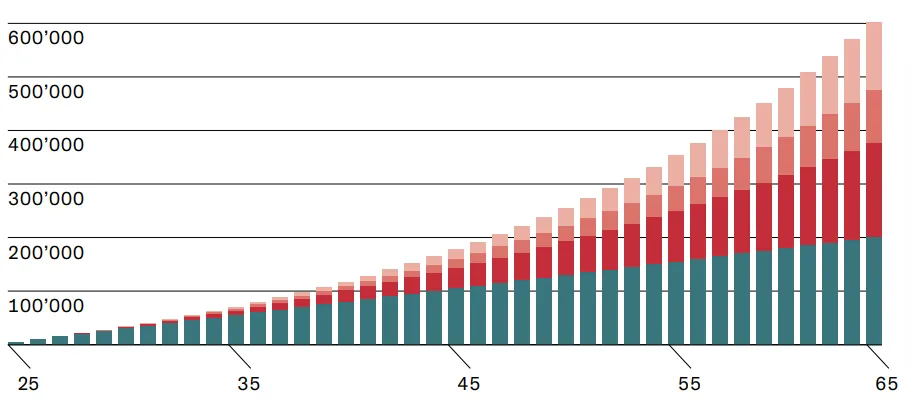
Your first job, your first salary, the pension fund starts deducting contributions. It’s safe to assume that it’s time to start saving for retirement. But it’s not that simple. Although risk cover for death and disability kicks in early on, specifically as of 1 January following your 17th birthday, according to the law, actual retirement saving begins at the age of 25, provided that you have a salary with an employer exceeding 22,680 Swiss francs. From this point onwards to the age of 65, the retirement credit on your co-ordinated salary will flow into the personal retirement account in the 2nd pillar, with your employer paying at least half of the contributions. The graph on the right shows how much an early start pays off: the compound interest effect makes the crucial difference over the years.

Small interest rate differences, big impact

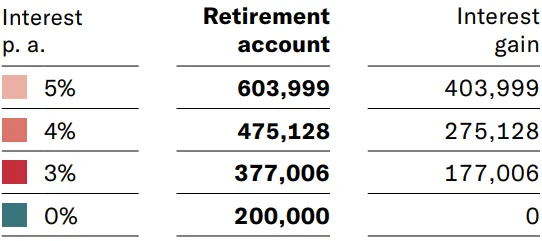
The prize for contributing to your 3rd pillar early on? Maximum compound interest. Over 40 years, retirement accounts in the 3rd pillar equate to a multiple of the contributions, as impressively illustrated by the graph.
null
25 is too early to be thinking about pensions.

MISCONCEPTION

Retirement account in the 3rd pillar after 40 years
null
Calculation example: based on an annual contribution of 5,000 Swiss francs at the end of each year from age 25 to 65. These return assumptions are hypothetical and do not constitute a forecast.

Structure of the 3rd pillar

  • Start early with your contributions into a Pillar 3a account.
  • Even small contributions are worthwhile. Continuity is important.
  • Review your investment strategy from time to time and adjust it if necessary.
  • As of 2026, contribution gaps in the 3rd pillar a can be topped up for the first time, and with retroactive effect for years from 2025.
  • Open multiple accounts/custody accounts so you can withdraw your retirement account balance in stages over several years later on.