
The answer is rarely luck. It’s all about good pension planning that makes more of the happy things in life and steps in quickly to cushion setbacks with a financial safety net.
We guide you through all your life stages and show which decisions you should ideally make when by way of your individual pension plan.
Whether it’s for you as an individual or a business owner or for your employees, PensExpert will always find the pension solution that suits you best.
Nowadays, people are living far beyond retirement
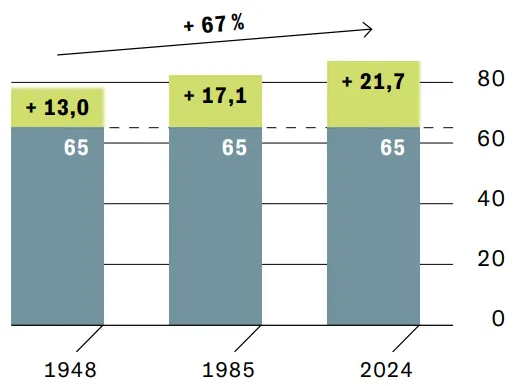
These days, anyone retiring at the age of 65 will have significantly more living ahead of them than previous generations did. When AHV/AVS insurance was introduced in 1948, the average life expectancy was around 13 years. By 2024, it had risen to 21.7, corresponding to a 67 per cent increase in life span.
There is a downside to this when it comes to pension benefits: anyone who stops working at the age of 65 is faced with financing on average more than two decades without any income from gainful employment. The capital saved must last much longer, all the more reason to actively plan your own retirement provision.
Life expectancy at the age of 65
I have little to no control over my pension benefits.
MISCONCEPTION
Occupational pension benefits 101
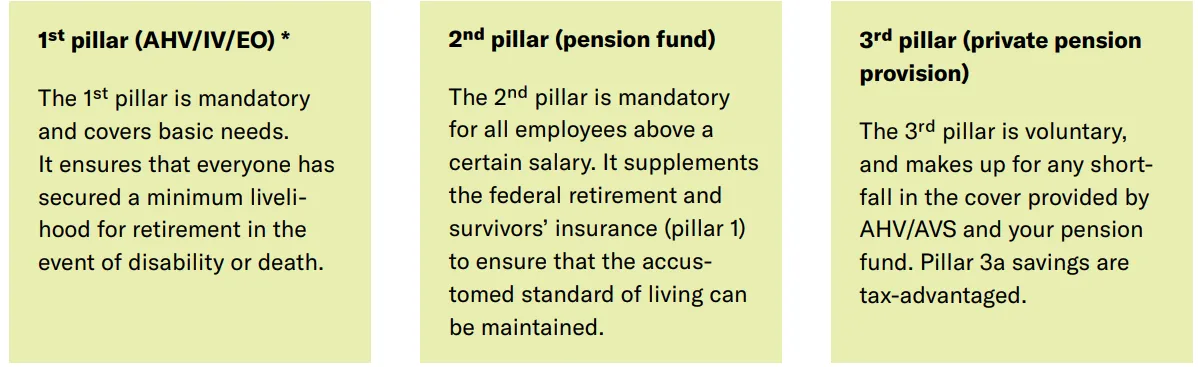
Retirement provision in Switzerland is based on three pillars. Each of these has its own task, and only in combination do they ensure standards of living are maintained in retirement.
There is a lot of money in the three pillars
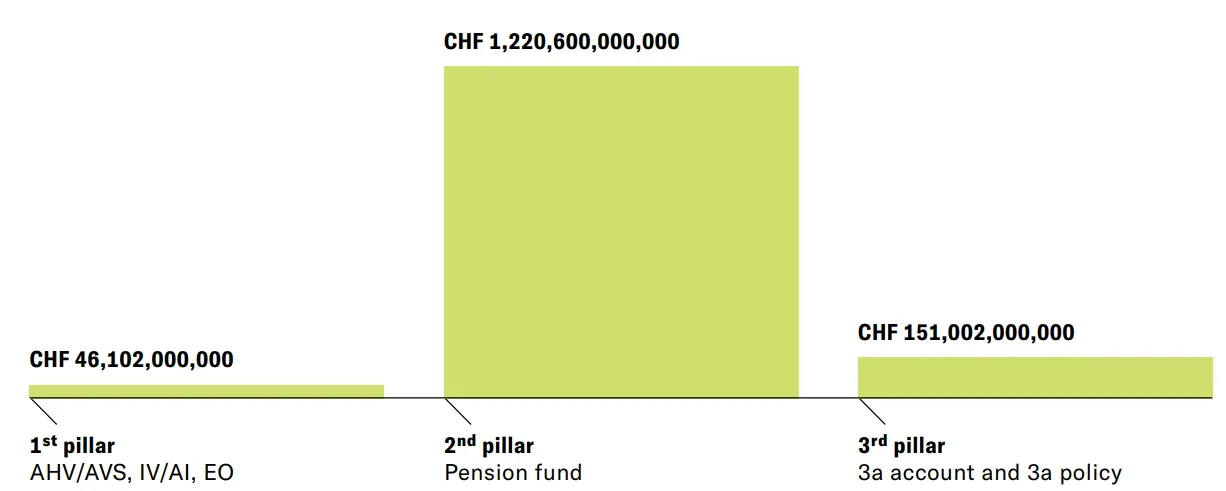
The graph shows how pension assets are distributed across the three pillars in Switzerland and highlights where the greatest capital is located: the 2nd pillar. For the many people in gainful employment, their pension fund is by far their largest asset, often exceeding the savings in their bank account.
The 1st pillar appears small because only the fund assets are shown here. Federal AHV/AVS insurance does not save any individual capital. It finances current pensions directly from current contributions. That’s why it’s worth having a closer look at the 2nd and 3rd pillars and looking into your own pension plan options.